

What changed for ISAs at Budget 2026?
Budget 2026, published on 28 October 2026, reversed the plan to cut the cash ISA limit to £12,000 for under-65s from April 2027. The cash limit stays at £20,000, the rules designed to stop people getting round the cap are dropped and the government will look at a new incentive for first-time stocks and shares ISA investors.
The Budget document puts it in one line: "the government has decided not to reduce the cash ISA limit, so that it remains at £20,000." A day later, HMRC's tax-free savings newsletter 24 spelled out the consequences for savers and ISA providers. It said the reduction "and associated anti-circumvention rules announced at Autumn Budget 2025 will not take effect".
That matters because a lot of pages written over the past year still describe the £12,000 cap as settled. Some of them are on gov.uk itself. So this guide does one thing: for every rule that was announced, it shows what was planned, what's true now and where to check it.
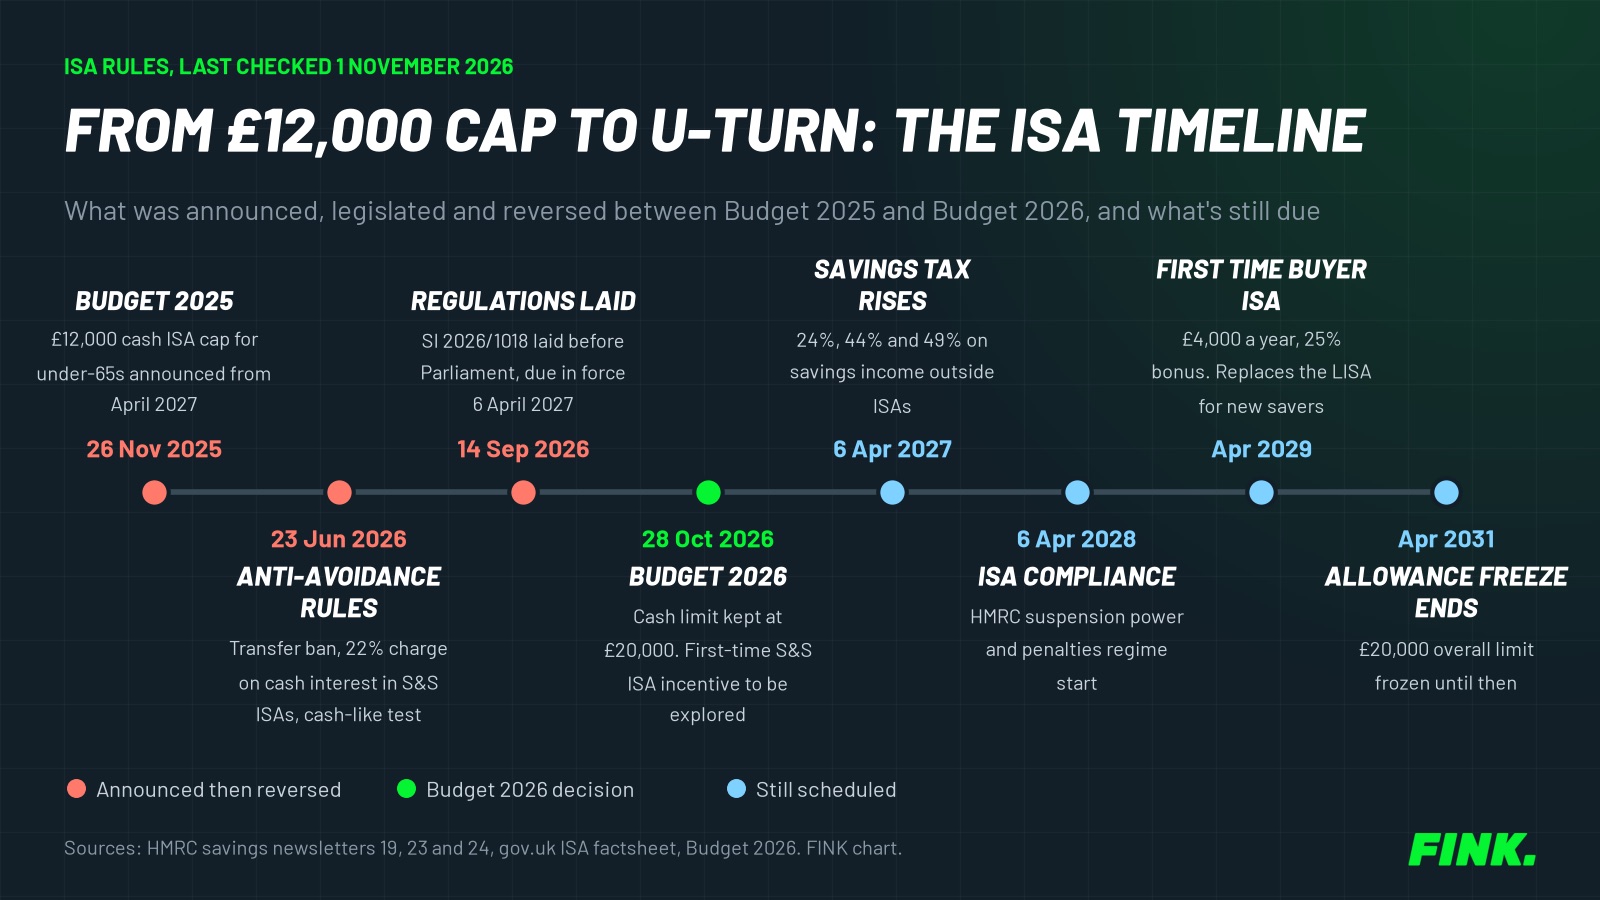
What was the original plan for April 2027?
At Budget 2025 on 26 November 2025, the government said the cash ISA limit would fall to £12,000 a year for savers under 65 from 6 April 2027, inside an unchanged £20,000 overall allowance. Savers aged 65 and over would keep a £20,000 cash limit.
HMRC's November 2025 newsletter listed three supporting rules, all aimed at under-65s:
- No transfers from stocks and shares or Innovative Finance ISAs into cash ISAs.
- Tests to decide whether an investment held in a stocks and shares ISA was "cash like".
- A charge on interest paid on cash held inside a stocks and shares or Innovative Finance ISA.
The detail followed on 23 June 2026. The charge was set at 22%, matching the basic rate of savings tax due from April 2027. "Cash like" was defined as money market funds, which could be held but not as 100% of the investments (gov.uk factsheet). The regulations were laid before Parliament on 14 September 2026 as SI 2026/1018, due to take effect on 6 April 2027 (HMRC newsletter 23).
The stated aim was to "incentivise investment in stocks and shares over cash savings and encourage better returns for savers", according to the explanatory memorandum for the regulations.
Old rule vs current rule: what's actually in force?
Every rule from the 2025 package is now either dropped or unchanged from today's position. The table below sets the planned rule beside the current one, with the source that confirms it. We last checked each line on the 1st of November 2026.
| Rule | Planned for 6 April 2027 | Current position | Source |
|---|---|---|---|
| Overall ISA allowance | £20,000 | £20,000, frozen until April 2031 | Newsletter 19 |
| Cash ISA limit, under 65 | £12,000 | £20,000 | Budget 2026 |
| Cash ISA limit, 65 and over | £20,000 | £20,000 | Newsletter 24 |
| Transfers from stocks and shares ISA to cash ISA | Banned for under-65s | Allowed | Newsletter 24 |
| Interest on cash in a stocks and shares ISA | 22% flat-rate charge | No charge | Newsletter 24 |
| Money market funds in a stocks and shares ISA | Allowed, but not as 100% of investments | Existing rules apply | Newsletter 24 |
| Junior ISA limit | £9,000 | £9,000, frozen until April 2031 | Newsletter 19 |
| Lifetime ISA limit | £4,000 | £4,000, frozen until April 2031 | Newsletter 19 |
The cap was scrapped in Budget 2026 and that decision stands. HMRC's newsletter 24 confirms the £12,000 limit won't take effect, so the full £20,000 can go into cash from April 2027.
Who would the £12,000 cap have affected?
Fewer people than the headlines suggested. HMRC's own impact note found that in 2022/23, 78% of cash ISA subscribers under 65 put in less than £12,000 and 22% put in more (HMRC tax information and impact note).
The money involved was larger than the head count. In 2024/25, £95.6bn went into cash ISAs against £37.2bn into stocks and shares ISAs. The average cash ISA subscription was £8,922 (HMRC Annual Savings Statistics 2026). HMRC linked the surge in cash ISA saving to Bank Rate and swap rates being at their highest in 2023/24 and 2024/25.
The government's own costing gives a sense of scale. The Budget 2026 policy costings estimate that keeping the £20,000 cash limit costs the Exchequer nothing in 2026/27, then rises each year to £70m by 2031/32:
| Tax year | Exchequer impact of keeping the £20,000 cash limit |
|---|---|
| 2026-27 | £0m |
| 2027-28 | -£5m |
| 2028-29 | -£20m |
| 2029-30 | -£35m |
| 2030-31 | -£50m |
| 2031-32 | -£70m |
The costing note says the tax base is interest on savings held by under-65s who'd otherwise have saved more than £12,000 a year into cash ISAs. It assumes those people now keep using cash ISAs up to the full £20,000. In other words, the Treasury doesn't expect the reversal to change much at the scale of the public finances.
Did the cap have evidence behind it?
The policy's logic was that people with large cash ISA balances would move some of that cash into investments if the cash route was capped. The case for and against rested more on judgement than on direct evidence. The government changed its view.
The argument for is the long-run gap between cash and shares. The argument against, made by providers and consumer groups, was that the rules added complexity and could push savers towards taxable accounts rather than into investments. Hargreaves Lansdown, for example, described the reforms as risking "complexity to a regime that is loved for its simplicity" (HL). The government's Budget document framed the reversal as continuing "generous support for savers" and said it would instead "explore a new ISA incentive for people investing in a stocks and shares ISA for the first time".
At FINK we look at it this way: a cap on one type of account changes where money sits, not how people decide what to do with it. If the aim is more people investing well, the harder problem is giving them a process they'll stick to when markets fall. No allowance rule solves that on its own.
What's still changing in 2027 and beyond?
Four changes are still scheduled. None of them changes what you can put in a stocks and shares ISA this tax year, but two affect the case for using the wrapper.
Higher tax on savings outside ISAs from April 2027
From 6 April 2027, savings income tax rates rise to 24% for basic rate, 44% for higher rate and 49% for additional rate taxpayers (HMRC newsletter 24). That's two points above the 22%, 42% and 47% announced a year earlier. The Personal Savings Allowance doesn't change. This only affects interest earned outside an ISA, so it increases the value of the shelter for cash savers above the allowance.
First Time Buyer ISA from April 2029
A new First Time Buyer ISA will replace the Lifetime ISA for new savers from April 2029, with £4,000 a year of contributions, a 25% government bonus and a £450,000 property price cap, per HMRC's summary. Existing Lifetime ISA holders keep their accounts. The full design and how it compares with a stocks and shares ISA for a house deposit are in our Lifetime ISA guide. Separately, from 29 October 2026 the Lifetime ISA withdrawal charge is 20% instead of 25% where you buy a first home above £450,000 (SI 2026/1130).
ISA manager compliance from April 2028
HMRC's power to suspend ISA managers, originally due in April 2027, now starts on 6 April 2028 with the wider penalties regime and digital ISA reporting. This sits with providers, not savers.
Allowance freeze until April 2031
The £20,000 overall limit is now frozen until April 2031. A frozen limit buys less each year when prices rise. Over time that makes it more likely that people with larger savings will hit it.
What should stocks and shares ISA investors take from this?
For most investors, nothing in the way they use a stocks and shares ISA has to change. The rules that would've affected them (the cash interest charge, the transfer ban and the money market fund test) won't start. The useful things to do are about process, not rules.
- Check the date on anything you read. Pages written between November 2025 and October 2026 may describe the £12,000 cap as fact. The gov.uk factsheet and impact note describing it were still live on the 1st of November 2026.
- Treat cash inside a stocks and shares ISA on its merits. With no 22% charge coming, holding some cash there comes down to your plan, not tax.
- Use transfers, not withdrawals, if you move money between ISA types. Gov.uk is clear that taking money out and paying it in elsewhere uses new allowance (gov.uk).
- Don't plan around the first-time incentive yet. There's no design, date or costing. We track it in the Starter ISA explainer.
- Plan for the tax year end as normal. The 2026/27 allowance still runs out on 5 April 2027. Our tax year end guide has the dates and the Bed and ISA guide covers moving existing holdings in.
For the wider picture of what to do inside the wrapper, see our stocks and shares ISA strategy guide.
Update log
- The 1st of November 2026: first published. Rules checked against Budget 2026, HMRC newsletter 24 and legislation.gov.uk. Budget 2026 scrapped the £12,000 cash ISA cap on 28 October 2026.