

Most people who start investing outside an ISA eventually ask the same question. Can I just move these shares in? The answer from gov.uk is no, with one narrow exception for shares from an employee scheme. The usual route is a bed and ISA, where the investments are sold outside the ISA and bought straight back inside it.
It sounds like admin. It's really a tax decision. Below are the tax, the costs and the order of moves, with figures checked on the 1st of November 2026 and the working behind every number.
What's a bed and ISA?
A bed and ISA is two deals done together:
- Your platform sells an investment in your general investment account (GIA).
- The cash goes into your stocks and shares ISA as a subscription.
- The platform buys the same investment back inside the ISA, usually straight away.
Gov.uk's ISA guidance says you can't transfer shares you already own into an ISA unless they came from an employee share scheme. That's why the sell and rebuy step exists. The money paid in counts towards your £20,000 ISA allowance for the tax year in the same way as cash from your bank.
The name comes from "bed and breakfasting", selling shares one evening and buying them back the next morning. The 30-day rule closed that off. A bed and ISA works because the ISA is treated differently, as covered below.
Why do people move investments into an ISA?
Because the tax gap between an ISA and a general account has widened. Inside an ISA there's no capital gains tax and no tax on dividends or interest. Outside, the allowances that used to cover most small investors are much smaller than they were.
| Tax outside an ISA | Allowance in 2026/27 | Rates above the allowance | Source |
|---|---|---|---|
| Capital gains tax | £3,000 annual exempt amount | 18% within the basic rate band, 24% above it | gov.uk |
| Dividend tax | £500 dividend allowance | 10.75%, 35.75% or 39.35% | gov.uk |
| Tax on savings income | Personal Savings Allowance | Basic rate due to rise to 24% from 6 April 2027 | Budget 2026 |
| All three inside an ISA | No limit on gains or income | 0% | gov.uk |
The savings income change matters for bond funds. Budget 2026 says the savings basic rate will be 24%, the higher rate 44% and the additional rate 49% from 6 April 2027. That's after Budget 2025 had already raised these rates by two points from the same date. Interest-paying funds held outside a wrapper will be taxed more heavily from then.
The case for moving isn't automatic, though. If your gains and dividends fit comfortably inside the allowances each year, the tax saved by moving may be small. It grows as the pot grows, which is why a lot of people do it gradually rather than all at once.
How much capital gains tax will a bed and ISA trigger?
This is the calculation that trips people up, so here's the method in full.
The gain on each holding is the sale value minus what you paid. HMRC's HS284 helpsheet explains that shares of the same company are pooled, so your cost is the average price across all your purchases. If you sell part of a pool, you take the same fraction of the pool's cost.
Then:
- Add up all your gains and losses for the tax year, including the bed and ISA sale.
- Subtract the £3,000 annual exempt amount.
- Add what's left to your taxable income.
- The part that falls inside the £37,700 basic rate band is taxed at 18%. The rest is taxed at 24% (gov.uk rates).
Gov.uk adds a useful point. You can set the exempt amount against the gains that would be charged at the highest rate.
A worked example
Say you hold UK shares worth £16,000 in a GIA. You paid £10,000 for them, so the gain is £6,000. There are no other gains this tax year.
- Basic-rate taxpayer with taxable income of £25,000. Taxable gain is £6,000 minus £3,000, which is £3,000. Added to income that makes £28,000, which is still under £37,700. Tax is 18% of £3,000, so £540.
- Higher-rate taxpayer. Same £3,000 taxable gain, all at 24%, so £720.
- Split across two tax years. Sell half this year. Half the pool is £8,000 of value with £5,000 of cost, so the gain is £3,000. That's covered by this year's exempt amount. Sell the other half after 6 April. If the price hasn't moved, that's another £3,000 gain covered by next year's exempt amount. Tax is £0.
In all three cases, buying £16,000 of UK shares back inside the ISA carries about £80 of stamp duty at 0.5%.
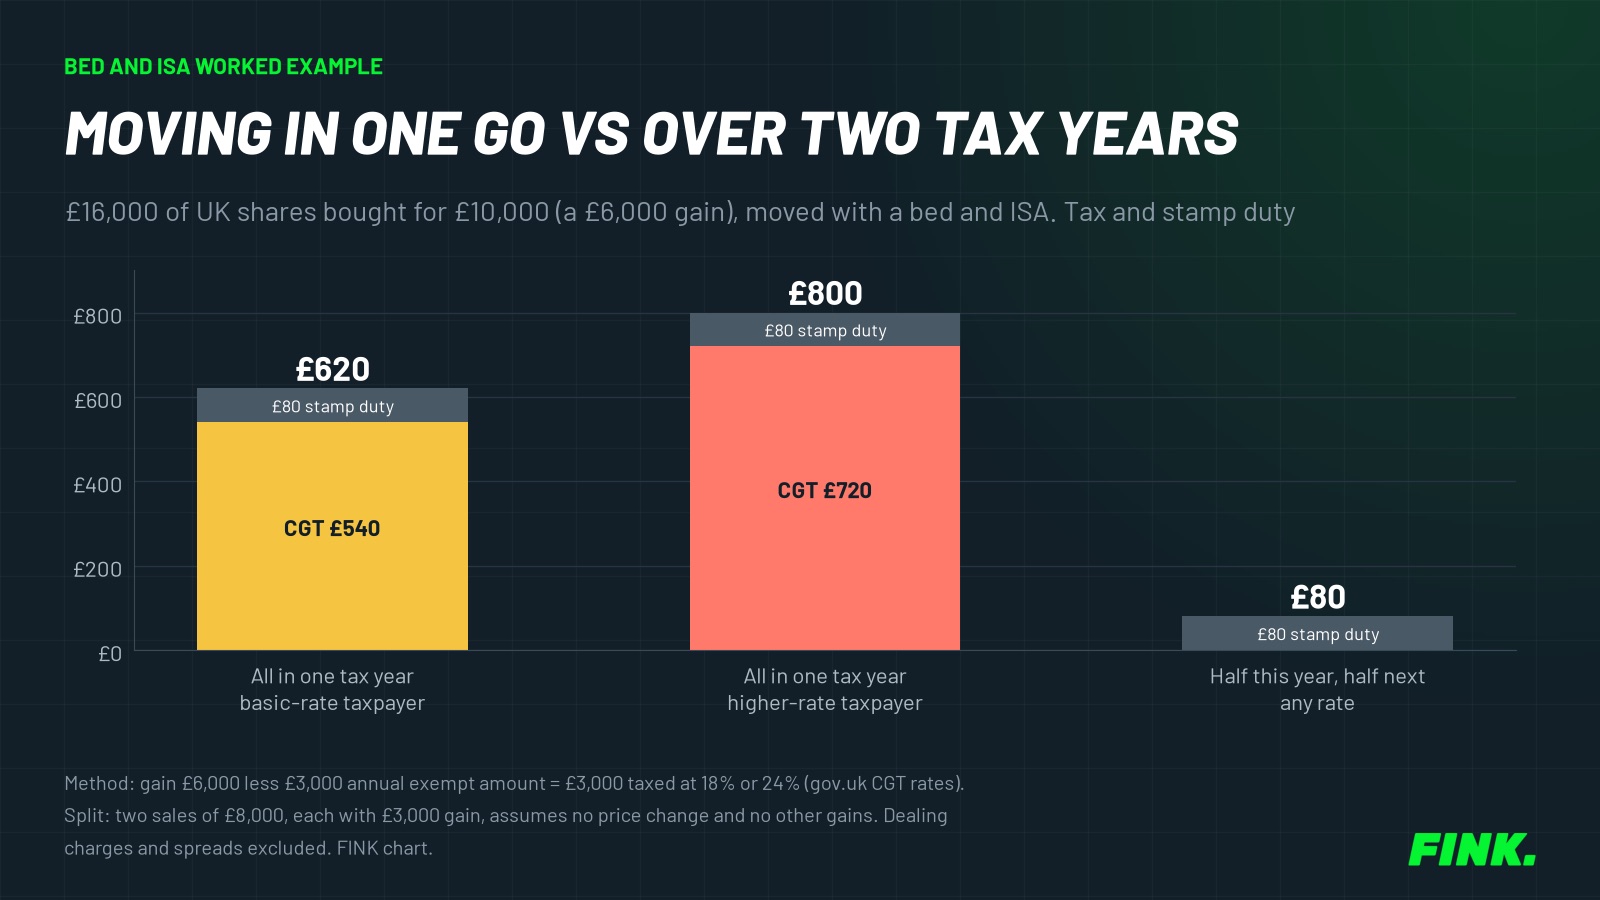
The split isn't free of risk. The half left outside stays exposed to tax for another few months. If it rises sharply before you move it, the second gain will be bigger than £3,000. The example also ignores dealing charges and the spread.
When you also need to report it
You don't get a bill for capital gains tax. Gov.uk says it's up to you to work out whether you owe it and report it. If you're registered for Self Assessment, you need to report gains on your tax return if the total amount you sold assets for was more than £50,000 in the year, even if the gain is under the allowance. A large bed and ISA can cross that line on its own.
Does the 30-day rule apply to a bed and ISA?
Not to the ISA purchase. HMRC's HS284 sets out the order for matching a sale with purchases. Shares bought on the same day come first. Shares bought in the next 30 days come second, under what it calls the "bed and breakfasting" rule. Only then does the sale come out of your pool.
Regulation 34 of the ISA Regulations 1998 changes this for ISAs. It says the pooling and matching rules apply separately to shares held in an ISA, "as if that person held them in a capacity other than that in which he holds any other securities of the same class". In practice the ISA rebuy isn't matched with the GIA sale, so the gain or loss on the sale stands.
Two things follow:
- A loss on the sale is real. Gov.uk says you can deduct an allowable loss from gains in the same tax year and carry unused losses forward. You can claim up to 4 years after the end of the tax year of the sale.
- The 30-day rule still applies outside the ISA. If you sold in the GIA and bought back in the GIA within 30 days, the sale would be matched with that rebuy instead.
What does a bed and ISA cost?
There are four costs. Only one of them is a tax.
| Cost | Description | Typical size | Source |
|---|---|---|---|
| Stamp duty (SDRT) | Charged on buying most UK shares electronically | 0.5% of the purchase | gov.uk |
| Dealing charges | Platform fees for the sale and rebuy | Varies. ii charges only the rebuy. AJ Bell's FAQ says one £5 charge per investment | ii, AJ Bell |
| Spread and price moves | The gap between sale and purchase prices | Small, but can mean slightly fewer shares | ii |
| Time out of the market | The delay between the two deals | Usually minutes for shares. Longer for funds | Platform terms |
Gov.uk says you don't pay stamp duty when you buy units in a unit trust or shares in an OEIC from the fund manager. It also says you don't normally pay it on foreign shares bought outside the UK. So the 0.5% applies mainly to UK-listed company shares.
ii's page says it works out how many shares it can rebuy after deducting the rebuy fee and stamp duty, so you may end up with slightly fewer shares in the ISA. AJ Bell's FAQ says it places requests within 10 working days and that funds such as unit trusts and OEICs can't go through its automated route. For those, you sell, pay the cash in and buy again. Check your own platform's page before you start, as these terms change.
Which holdings should you move first?
If you can't move everything this tax year, the order matters. There's no single correct ranking, but the tax rules point to a sensible way of thinking about it.
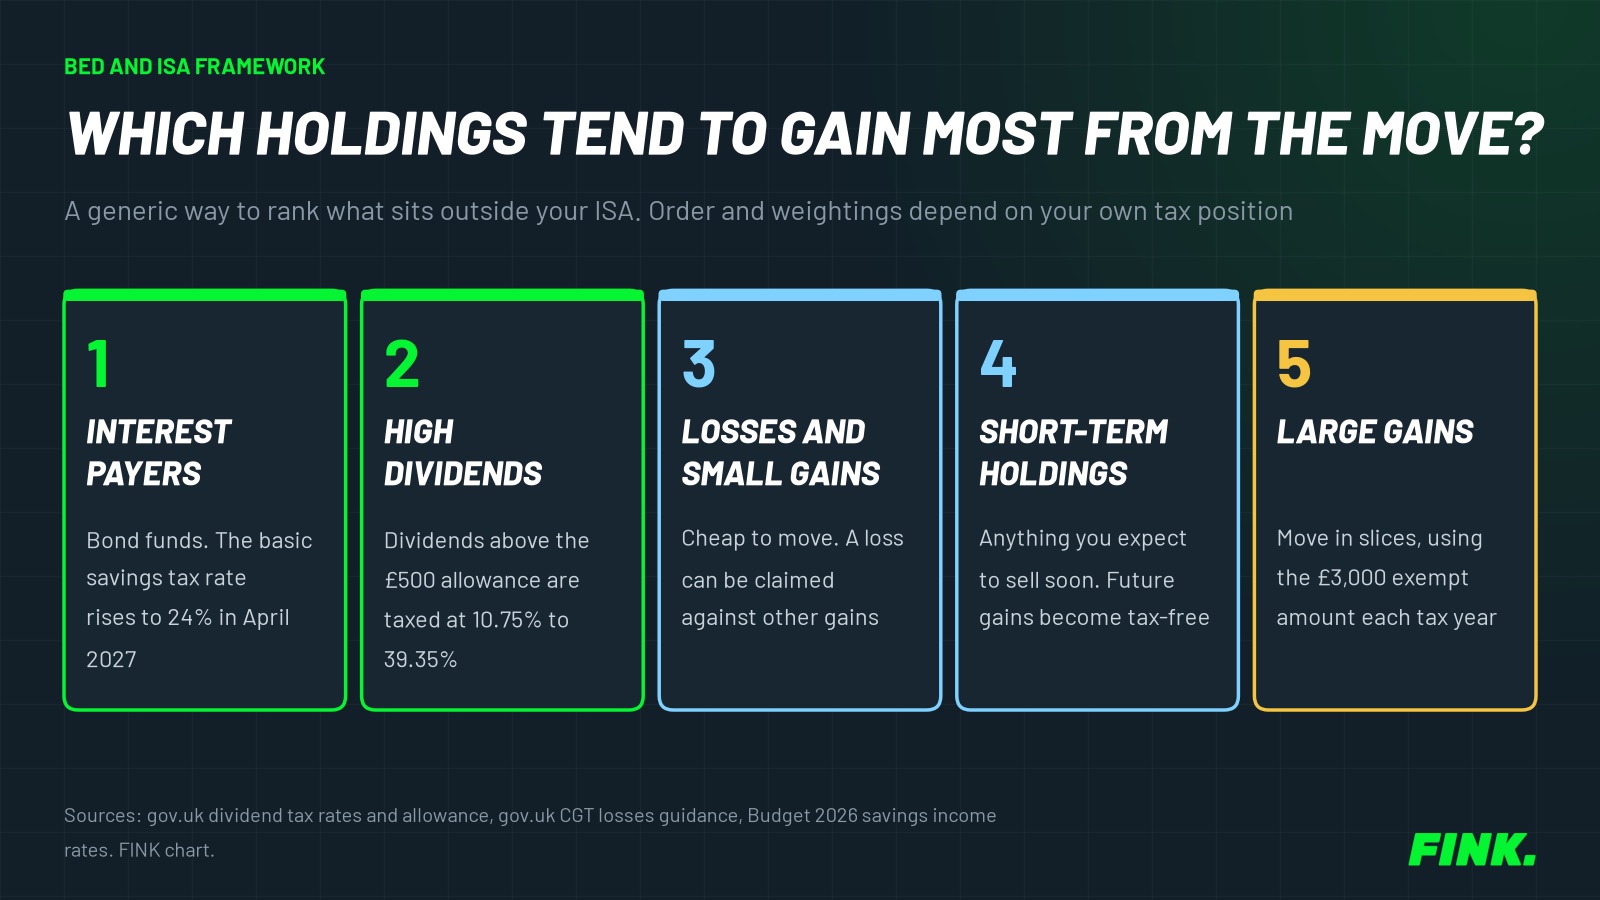
- Interest payers. Bond funds that pay interest are hit by savings income rates, which are rising to 24%, 44% and 49% from April 2027.
- High dividend payers. Every pound of dividends above £500 is taxed outside an ISA. A holding with a high yield uses that allowance fastest. Our ISA dividends guide shows the yearly tax at different portfolio sizes.
- Losses and small gains. These cost little or nothing to move. A loss can reduce tax on other gains.
- Holdings you expect to sell soon. If you're likely to sell within a year or two, moving first means that future gain is tax-free. Once inside, the sale itself works as described in selling shares in a stocks and shares ISA.
- Large gains. These are often moved in slices, using each year's £3,000 exempt amount, unless the yearly tax saving from moving them is bigger than the one-off tax cost.
At FINK we look at it this way: the bed and ISA decision is part of the same process as choosing what to buy. Writing down why each holding sits where it does makes this order easier to settle each April.
There's a counter-argument to moving at all. If a holding has a large gain, a small dividend and you've no plan to sell it, paying tax now to shelter it may never pay back.
Can couples use a bed and ISA together?
Yes. It doubles the room. Gov.uk says you don't pay capital gains tax on assets you give to your spouse or civil partner, unless you were separated for the whole tax year. Each partner has their own £3,000 exempt amount and £20,000 ISA allowance.
That means a couple can sometimes move twice as much in one tax year without tax. The partner receiving the shares takes on the original cost, so the gain doesn't disappear. It just becomes theirs. Gov.uk also notes you can't claim a loss on assets given to a spouse. If the transfer is part of a wider plan, such as moving income to the lower earner, it's worth getting tax advice.
When is the best time to do a bed and ISA?
Doing it earlier in the tax year has some advantages:
- More time sheltered. Every month inside the ISA is a month of dividends and gains free of tax.
- Platform cut-offs. AJ Bell's FAQ says requests are placed within 10 working days. Leaving it until late March can mean missing 5 April.
- Two allowances around the deadline. A sale just before 5 April and another just after use two years' £3,000 exempt amounts and two years' ISA allowances. Our end of tax year guide covers the dates for 2026/27.
The trade-off is that a bed and ISA leaves less allowance for new cash that year. If you've got both, the deciding question is which would cost more tax to leave outside.
How do you do a bed and ISA step by step?
- List what's outside. Note each holding's value, average cost and the dividends or interest it paid last year.
- Work out the gains. Use the pooled cost method above. Add any other gains or losses you've made this tax year.
- Decide the amount. Check how much ISA allowance you've got left and how much gain you can take within £3,000.
- Check your platform's process. Some have a bed and ISA button. Others need a form or a phone call. Funds may need selling and rebuying separately.
- Place the request. Confirm the costs shown, including stamp duty on UK shares.
- Keep the contract notes. You'll need the sale price and date for your capital gains records. Keep the rebuy price for your ISA records.
- Report if needed. If your gains are over £3,000, or total sales are over £50,000 and you're in Self Assessment, it goes on your tax return.
For how the moved holdings fit the rest of the ISA, our guide to running a stocks and shares ISA covers the overall process. If you're deciding between holding shares directly or through funds once they're inside, see individual shares or funds.
What are the downsides of a bed and ISA?
Here they are, plainly.
- You may pay tax now to save tax later. That only pays off if the holding produces enough gains or income in future.
- Stamp duty is a certain cost. On UK shares, 0.5% is paid upfront in return for a tax saving that depends on future returns.
- It uses your ISA allowance. Money spent moving old holdings can't also be used for new savings in the same year.
- Price risk between the deals. Usually tiny for shares done the same day. It can matter more for funds that take days to sell and rebuy.
- Records get more complex. You'll need clear notes of what moved, when and at what price.
None of these is a reason to avoid it. They're reasons to do the sums first.