

What's a stocks and shares ISA strategy?
A stocks and shares ISA strategy is the set of decisions you make about the money inside the wrapper. That covers what it's for, how it's split, how much goes into each holding, when you check it and when you sell. The ISA is just the tax shelter. The strategy is everything you do inside it.
That sounds obvious, but search for "stocks and shares ISA strategy" and most of what comes back answers a different question. You get platform comparisons, lists of popular funds and model portfolios with the percentages already filled in. They're useful if you've already decided how you invest. They don't help you decide.
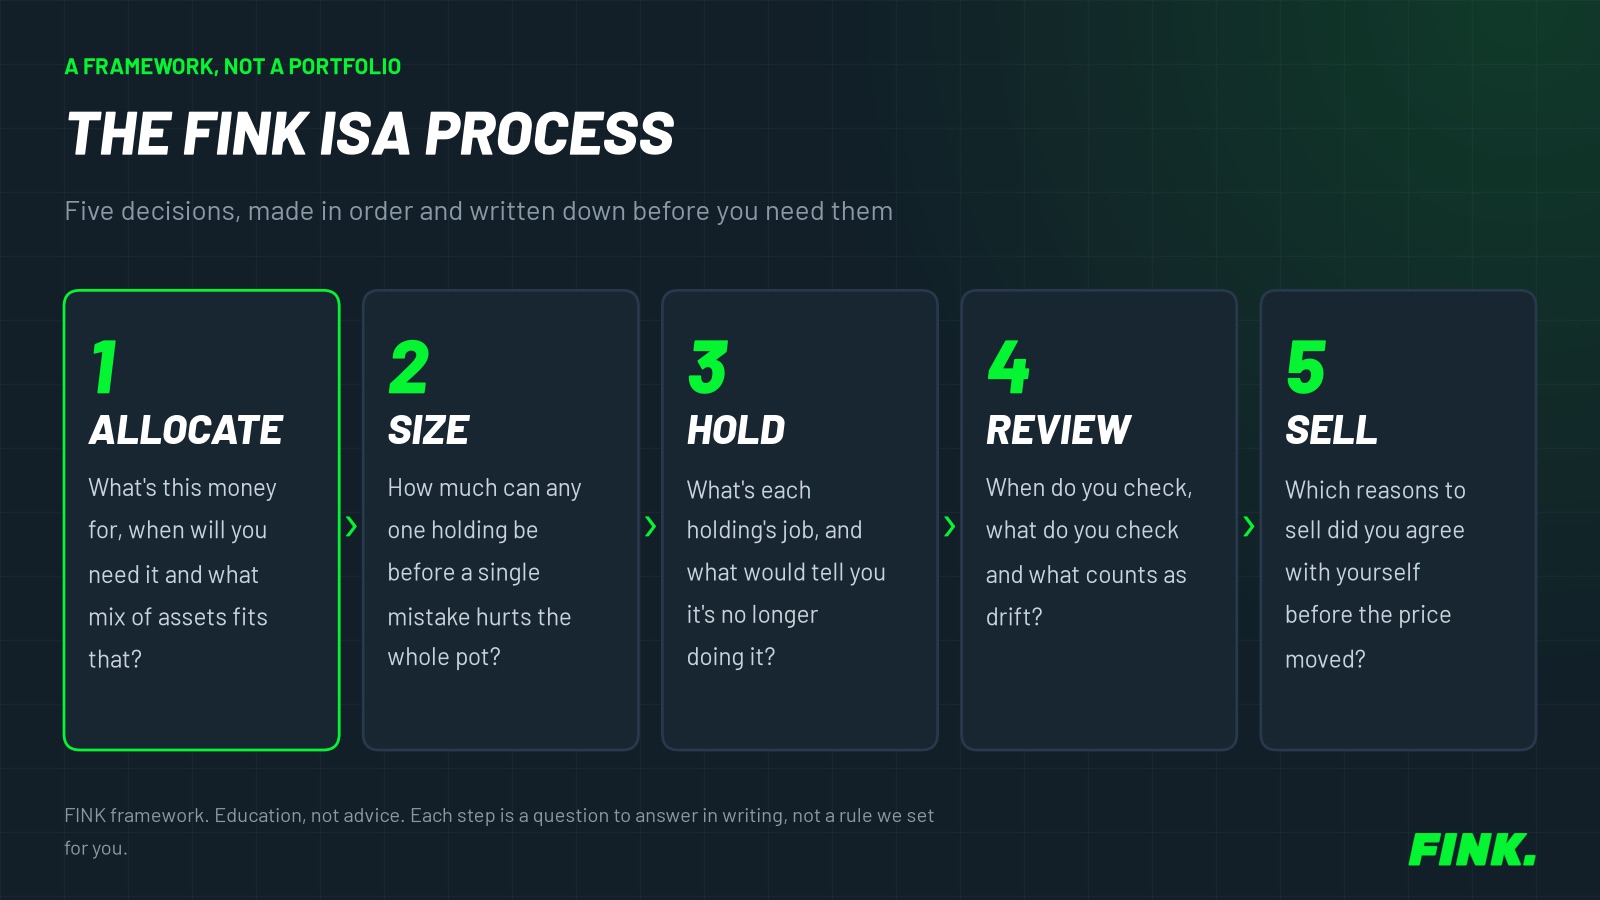
This guide takes the other route: it starts with what the official data and published research actually say, then turns that into a short process you can write down. At FINK we call it the ISA Process: Allocate, Size, Hold, Review, Sell. It's not a portfolio. It's five questions, asked in order.
What are the ISA rules for 2026/27 after Budget 2026?
The overall ISA allowance for 2026/27 is £20,000 (gov.uk) and it's frozen at that level until April 2031 (HMRC newsletter 19). Budget 2026 scrapped the planned £12,000 cash ISA cap, so the full £20,000 can go into cash and you can still split it between cash and investments in any proportion.
Savings tax outside ISAs rises from April 2027 and the government is exploring a new incentive for first-time investors. The full before and after, with every source, is in our guide to ISA changes for 2027.
What does the data say about how people use their ISAs?
Three facts from HMRC frame every strategy question that follows. Most new ISA money still goes into cash. Most savers put in far less than the maximum. Stocks and shares ISAs still hold the larger share of the total pot.
The HMRC Annual Savings Statistics, published on 16 September 2026, cover the 2024 to 2025 tax year (provisional) and earlier:
| Measure (adult ISAs) | Figure | Year |
|---|---|---|
| Total subscribed | £135.7bn | 2024/25 |
| Subscribed to cash ISAs | £95.6bn | 2024/25 |
| Subscribed to stocks and shares ISAs | £37.2bn | 2024/25 |
| Share of accounts subscribed to that were cash | 64% | 2024/25 |
| Share of total ISA market value in stocks and shares | 55.8% | End of 2024/25 |
| Subscribers who paid in the maximum | 28.8% | 2023/24 |
| Most common subscription band | £1 to £2,000 (30.7% of savers) | 2023/24 |
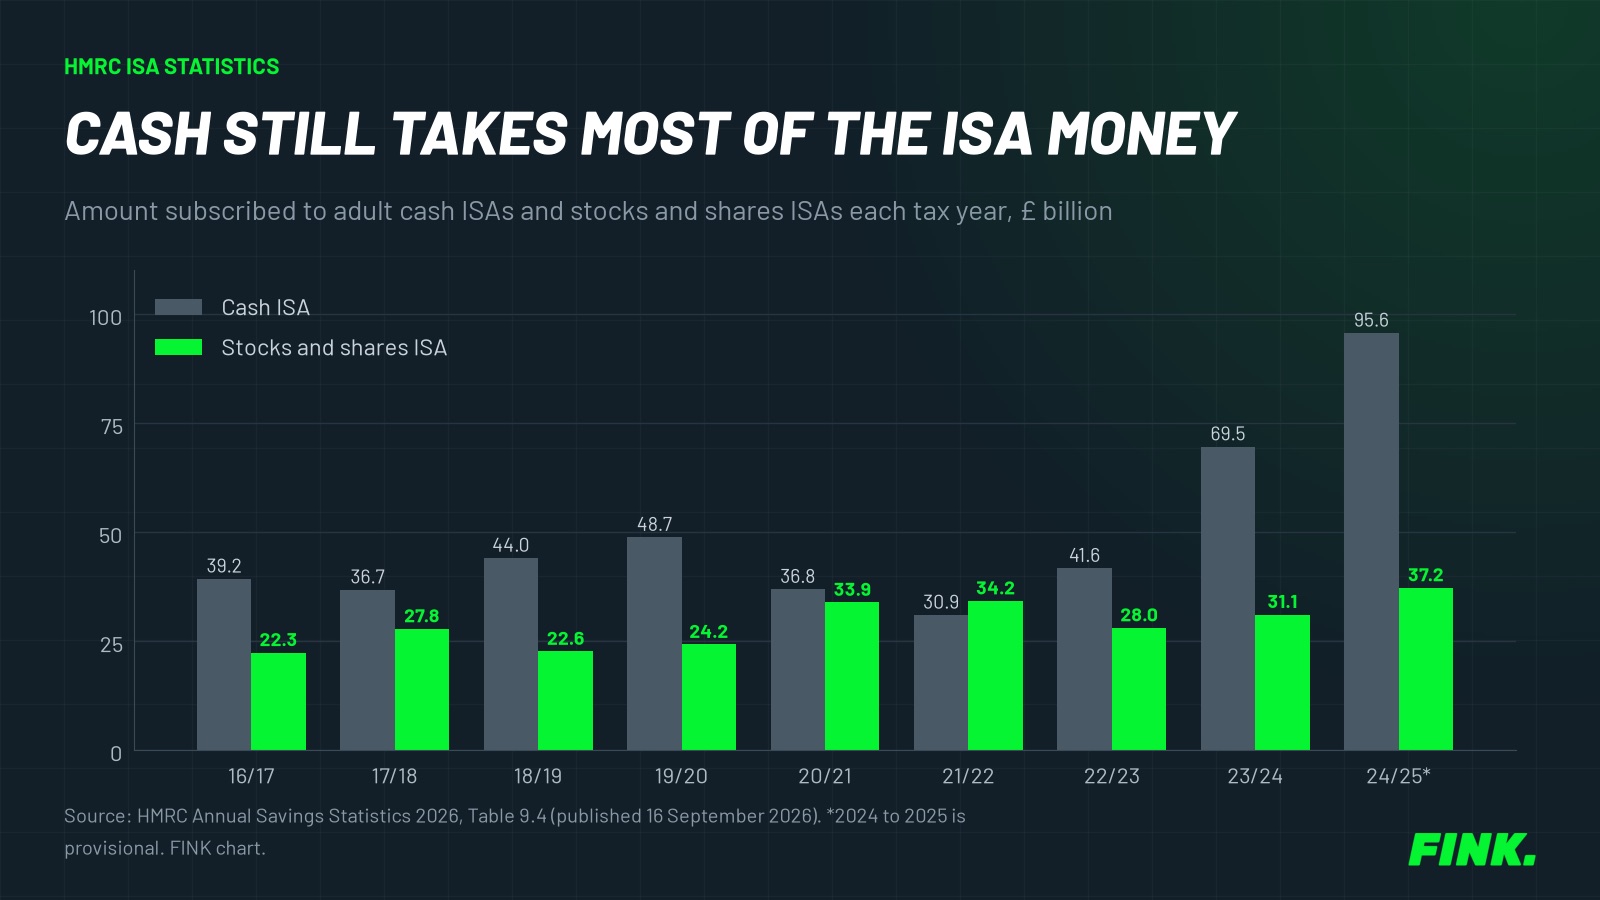
HMRC puts the cash surge down to Bank Rate and swap rates, which were at their highest during 2023/24 and 2024/25. That's a fair reading. When cash pays well, the case for taking market risk gets weaker for short-term money and nobody needs a strategy to explain that.
What the table also shows is that the "how do I use my £20,000" question applies to a minority. Fewer than three in ten subscribers paid in the maximum in 2023/24. For most people the question is how to invest a few thousand pounds a year well. That's mostly about structure.
At the other end, HMRC's count of ISA millionaires shows what decades of large contributions have added up to for a few thousand people. For first-time investors, the incentive the government is exploring is tracked in our Starter ISA guide.
Why the wrapper matters more from 2027
The gap between saving inside and outside an ISA widens in April 2027 when the savings tax rates rise by another two percentage points. The Budget document says a basic rate taxpayer would need over £25,000 in savings outside ISAs before paying tax, thanks to the Personal Savings Allowance. Above that, the ISA shelter does real work. For investments, gains and dividends inside an ISA are free of UK tax, as LITRG explains. Outside one you'd face the £3,000 capital gains allowance and the £500 dividend allowance (gov.uk CGT, gov.uk dividends).
Step 1, Allocate: what's the money for and how should it be split?
Allocation means deciding which part of your money goes into cash, which into investments and what mix of investments you'll hold. It comes first because it decides most of the ride you'll have, far more than any single fund choice.
Three questions do most of the work:
- When will you need it? Money for a house deposit in two years and money for retirement in 25 years are different problems. The Lifetime ISA and the coming First Time Buyer ISA (from April 2029, per HMRC newsletter 24) exist because house money behaves differently.
- How would you react to a large fall? Not how you think you'd react. How you actually did last time, if there was a last time.
- What else do you already own? A workplace pension invested in a global equity fund is already part of your allocation, even though it isn't in your ISA.
Allocation isn't a one-off decision. Left alone, it changes itself: in Vanguard's long-run test, a 50/50 portfolio that was never rebalanced ended up mostly in shares (Vanguard, 2015).
Our rebalancing guide has the figures and a worked example. For the cash part of the split, cash ISA vs stocks and shares ISA sets out the long-run record. Lifetime ISA vs stocks and shares ISA covers house money. If retirement is the goal, ISA vs SIPP does the tax arithmetic.
Where FINK sits on this
We think the allocation step is where most investors improvise. They pick funds first and discover their allocation afterwards. Writing the split down first, as a target, is what makes the later steps (sizing, reviewing, selling) possible, because each one is measured against it.
Step 2, Size: how much should go into any one holding?
Sizing is deciding the most you'll put into any one fund or share before you buy it. It caps what a single wrong call can do to the whole ISA. Diversification research gives the shape of the answer, though not a magic number.
The classic evidence is Meir Statman's 1987 paper, which concluded at least 30 to 40 shares were needed to diversify, against the earlier rule of thumb of about ten (Statman). Later work moved the number up, not down. The full research trail and the diversification curve are in how many shares to hold in a stocks and shares ISA.
Two practical points come out of that research:
- Most of the benefit comes early. Going from one share to ten roughly halves the expected volatility in Statman's table. Going from 50 to 100 barely moves it.
- Funds change the maths. If most of your ISA sits in a global tracker, it already holds thousands of companies. Individual shares around it are a question of how much each one could move the total, not of diversification from scratch.
We don't publish a single sizing percentage. The right cap depends on how many holdings you run, how volatile each one is and how much a loss would hurt you. What we do say: the cap gets set before the buy, written down and applied to the holdings you love as well as the ones you're unsure about.
Position sizing has its own guide, how much to invest in one stock, with a loss table and a risk-budget method. If you're choosing between shares and funds in the first place, individual shares or funds in your ISA weighs the evidence and the platform costs.
Step 3, Hold: what job does each holding do?
Holding well means each fund or share has one clear job and you've written down what would show it's no longer doing that job. Without that, every price move becomes a fresh debate.
A useful test is to describe each holding in one line:
| Holding type | Typical job | What would show it's not doing the job |
|---|---|---|
| Global equity tracker | Broad long-term growth at low cost | Charges rise or tracking error widens against its index |
| Bond or gilt fund | Steadier value, income, a buffer in some falls | Its role in your plan changes (for example a shorter time horizon) |
| Regional or sector fund | Deliberate tilt you've chosen on purpose | The reason for the tilt no longer holds |
| Individual share | A specific business you understand | The reason you bought it no longer holds, not just the price |
The table also catches overlap. On our check of two State Street funds, a global tracker and an S&P 500 tracker side by side left about 82% of the money in US-listed companies. That might be exactly what you want. It just isn't diversification in the way two fund names suggest.
The method is in how many funds in a stocks and shares ISA. ISA fund overlap compares the most popular trackers. A core and satellite structure is one way to give each holding a separate job. For what goes into the core and how to read a company before buying, see what to invest in a stocks and shares ISA. Income holdings raise a separate question, covered in dividends in a stocks and shares ISA.
Should you put a lump sum in or invest monthly?
If you already have the money, the historical evidence favours investing it sooner. If you're investing from salary, monthly is simply how the money arrives, so there's nothing to choose.
Vanguard has tested this twice, with UK data to 2011 and global data to 2022. Both times the lump sum came out ahead in roughly two periods out of three (Vanguard, 2012, Vanguard, 2023).
Now the counter-evidence. That still leaves roughly a third of periods where phasing in did better. Those tend to be the painful ones.
Investors with strong loss aversion can reasonably prefer phasing in because it reduces regret. That's a real cost, not a weakness. If a bad first month would make you abandon the plan, a slower start that you stick with beats a faster one you don't.
The full decision flow is in lump sum or drip feed into your stocks and shares ISA. If the money comes from salary, how much to put in each month starts from your budget. New to all this? Your first year with a stocks and shares ISA sets out the first twelve months step by step.
Step 4, Review: how often should you check and rebalance?
A review is a scheduled check of your ISA against the targets you wrote in Step 1. The research suggests that how often you rebalance matters less than having a rule at all.
Vanguard's rebalancing research found "no optimal frequency or threshold" and suggested checking once or twice a year and acting on drift of about five percentage points (Vanguard, 2015). Inside an ISA, selling doesn't trigger capital gains tax, so the remaining costs are dealing charges and your time. You can often avoid both by pointing new money at whatever's underweight instead of selling.
A simple review covers four things:
- Current split against your written target.
- Any single holding that's grown beyond the size cap you set in Step 2.
- Charges on each fund and on the platform.
- Whether anything in your life has changed the time horizon from Step 1.
There's a worked example with real arithmetic in how to rebalance a stocks and shares ISA. There's a twelve-point yearly list in our annual ISA review checklist.
Step 5, Sell: when should you sell inside an ISA?
In this process, a sale happens when a reason agreed in advance has come true. The usual list: the reason for owning it no longer holds, it's outgrown the size cap, the money's needed or something clearly better deserves the space. Selling because the price fell or because the news is loud isn't on that list.
The ISA makes selling cheaper but not easier. There's no tax to weigh, which removes one excuse for holding on. The behavioural problem is still there: investors tend to sell winners too soon and hold losers too long (Odean, 1998).
A list written before the price moves is the most direct defence we know of. The mechanics of a sale (tax, settlement and costs) are in selling shares in a stocks and shares ISA. If the whole ISA is down, start with stocks and shares ISA losing money.
Remember the trade-off on losses. A loss realised inside an ISA can't be set against gains elsewhere (LITRG). That's rarely a reason to keep a loser, but it's worth knowing if you also hold investments outside an ISA.
Selling gets its own guide: When to sell a stock.
What about the end of the tax year?
The 2026/27 tax year ends on 5 April 2027. Allowance you haven't used by then is gone, as it doesn't roll over. Your existing ISA keeps its tax-free status regardless (gov.uk).
Two details trip people up:
- Platform cut-offs for new money and transfers often fall a few working days before 5 April. Check yours.
- Flexible ISAs let you take cash out and put it back in the same tax year without using more allowance. Not every ISA is flexible. Our withdrawal rules guide works through gov.uk's example. If you hold ISAs with several providers, how many stocks and shares ISAs you can have covers the rules on paying into more than one.
If you hold investments outside an ISA, the end of the tax year is also when people use Bed and ISA to move them in. Our tax year end guide covers the dates.
What do the common ISA strategies get right and wrong?
The popular approaches each solve one problem well and leave others open. None of them is wrong. Each just answers a narrower question than "what's my strategy?"
| Approach | What it does well | What it leaves open |
|---|---|---|
| One global tracker | Low cost, very broad, little upkeep | Heavy US and big-tech weighting. No plan for falls or for when you'll need the money |
| Ready-made multi-asset fund | Allocation and rebalancing done for you | Higher charges than a tracker. You still decide when to add or withdraw |
| Several funds by region or theme | Control over tilts | Overlap you may not see, plus drift to manage |
| Core tracker plus individual shares | Room for your own ideas without betting everything | Needs a size cap and sell rules or the "satellite" can quietly become the core |
| Individual shares only | Full control and understanding of what you own | Needs more holdings and more time to reach the diversification the research describes |
The first row deserves a note. The Budget 2026 document notes that the government launched targeted support in April to help more people with investment decisions. It also welcomed the industry-led "Invest for the Future" campaign.
Expect a lot of "just buy a global tracker" advice in the next year. It's a sensible default for many people. It still isn't a strategy until you've decided how much goes in, when and what you'd do in a bad year.
A one-page ISA plan you can write today
Here's the process as a template. Fill it in once, keep it somewhere you'll see it and change it only at a review, not in the middle of a market move.
- Allocate: This ISA is for __. I expect to need it in _ years. My target split is % shares, % bonds, ___% cash or other.
- Size: No single fund will be more than __% and no single share more than ____% of the ISA, measured at each review.
- Hold: Each holding's job is written next to it. I'll know it's failing if ______.
- Review: I'll check on __ (date) every _ months. I'll act if any part of the split is more than ___ points from target.
- Sell: I'll sell or trim if the reason I bought it no longer holds, if it breaks my size cap, if I need the money or if ______.
The blanks are deliberate. The numbers that suit a 30-year-old with a pension and a 60-year-old without one aren't the same. Anyone who fills them in for you without knowing your situation is guessing.